5 AEP Mistakes to Avoid During Medicare Annual Enrollment in Metro Detroit
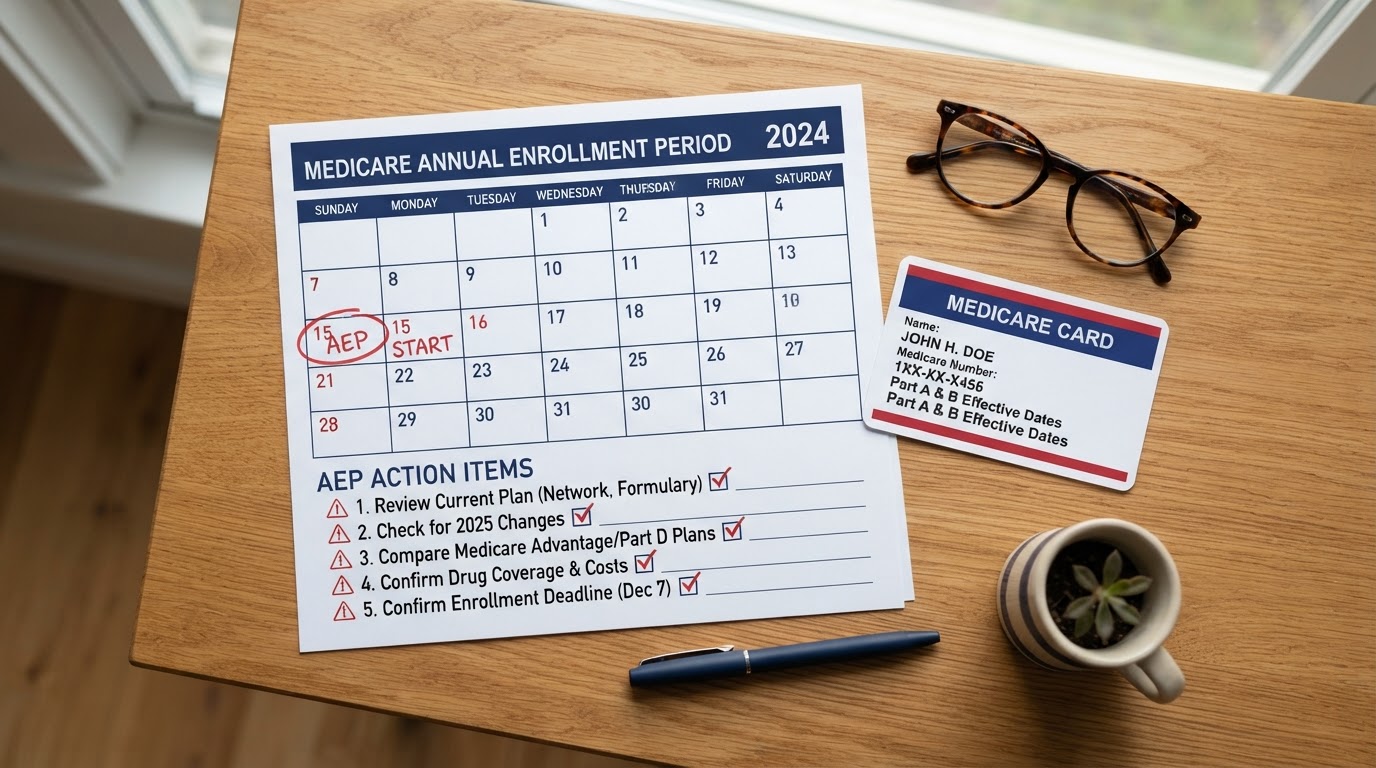
If you're on Medicare, you probably already have a stack of mail sitting on your kitchen counter, an ANOC letter, a plan comparison flyer, maybe a postcard reminding you that Annual Enrollment is open. It's easy to let it all sit there until December, and that's exactly how good people end up with the wrong coverage for the coming year. This week is National Retirement Security Week, and Medicare's Annual Enrollment Period, AEP, is open right now, October 15th through December 7th. When I help Metro Detroit retirees sort through their Medicare coverage, I see the same five mistakes come up again and again. None of them are complicated to fix, once you know to look for them.
Why National Retirement Security Week Matters This AEP Season
National Retirement Security Week is a national effort held every October to encourage people to take a closer look at their retirement readiness, savings, income and coverage alike. It's not tied to any one company or product; it's simply a reminder that retirement security is something people build through informed decisions, not something that happens automatically.
This year, that awareness week overlaps with the opening weeks of Medicare's Annual Enrollment Period, which runs October 15th through December 7th. During AEP, anyone on Medicare in Wayne, Oakland or Macomb counties can review their coverage and make a change for the coming year, whether that's switching Medicare Advantage plans, moving between Medicare Advantage and Original Medicare, or updating a Part D prescription drug plan.
Most of the mistakes below don't come from a bad decision. They come from a decision made too fast, or not made at all, because the paperwork felt overwhelming. That's worth fixing, and it's exactly what the rest of this article walks through.
Mistake 1 and 2: The ANOC Letter and the Premium Trap
Every September, Medicare plans are required to mail current members an ANOC letter, short for Annual Notice of Change. It spells out exactly what's different about the plan for the coming year: premium, deductible, copays and which doctors, hospitals and pharmacies remain in network. If that letter goes unopened, the plan simply auto-renews as-is, even if the plan itself has changed. Setting aside fifteen minutes to actually read it is one of the highest-value things a Medicare beneficiary can do all year.
The second mistake is choosing, or staying with, a plan based on the premium alone. A $0 premium plan can look like an easy win, but if your cardiologist, your preferred hospital system or your regular pharmacy isn't in that plan's network for next year, the low premium doesn't actually save money, it just shifts the cost to appointments and prescriptions instead. Before locking in a plan for next year, check the specific providers and pharmacy you use against that plan's network directory for next year, not this year's directory.
Mistake 3 and 4: Formulary Changes and the AEP vs. MA OEP Mix-Up
The third mistake is skipping a formulary check. A formulary is the specific list of drugs a plan covers, and it's updated every year, sometimes significantly. A prescription that sat in a lower cost tier this year can move to a higher tier next year, or be removed from the formulary entirely. Anyone taking regular prescriptions should look up next year's formulary and check each medication by name before choosing or renewing a plan.
The fourth mistake is the one that causes the most confusion: mixing up AEP with the Medicare Advantage Open Enrollment Period. AEP runs October 15th through December 7th and is open to everyone on Medicare, for any type of plan change. The Medicare Advantage Open Enrollment Period is a separate window that runs January 1st through March 31st, and it only applies to people already enrolled in a Medicare Advantage plan. During that spring window, a person gets exactly one plan change, either to a different Medicare Advantage plan or back to Original Medicare, and the rules governing it are different from AEP's. Treating the two windows as interchangeable is a common and avoidable mistake.
Mistake 5: Why Reviewing Early Matters More Than You Think
The fifth mistake is waiting until the final week of AEP to sit down and actually review coverage options. This isn't about pressure or a countdown, it's simple math: AEP runs for about seven and a half weeks. Reviewing coverage early in that window means that if a problem turns up, a doctor who left the network, a prescription that dropped off the formulary, there's still time to fix it before December 7th. Reviewing in the final days removes that cushion entirely.
Put another way, reviewing early isn't about rushing into a decision. It's what creates the room to slow down, ask questions and make a calm, informed choice, rather than a last-minute one.
Frequently Asked Questions
When does Medicare AEP end in Michigan?
Medicare's Annual Enrollment Period is a national window, the same everywhere including Michigan. It runs October 15th through December 7th every year, and any changes made take effect January 1st of the following year.
What's the difference between AEP and the Medicare Advantage Open Enrollment Period?
AEP (October 15 to December 7) is open to everyone on Medicare for any plan change. The Medicare Advantage Open Enrollment Period (January 1 to March 31) is a separate, narrower window that only applies to people already enrolled in a Medicare Advantage plan, and it allows exactly one plan change during that spring period.
How do I know if my doctor is still in-network for next year?
Check the plan's provider directory for the coming year, not the current year's directory, since directories are updated annually. Your ANOC letter and the plan's website are the two most reliable places to confirm.
What is an ANOC letter and do I need to read it?
ANOC stands for Annual Notice of Change. Every Medicare plan is required to mail one to current members each September, listing what's changing for the coming year. Yes, it's worth reading in full, it usually takes about fifteen minutes and covers most of what you need to know before AEP ends.
Can I change my Medicare plan more than once during AEP?
Yes. During AEP, you can make as many changes as you'd like, and whichever choice is on file when the window closes on December 7th is the one that takes effect January 1st.
Ready to Avoid These Mistakes?
If you'd like help reviewing your Medicare coverage before December 7th, and how it fits with the rest of your retirement picture, book a free Six-Pillar Retirement Review at LifestyleSafety.com or call (313) 450-9543. Janine Davis is an RSSA and the owner of Lifestyle Safety LLC, a Metro Detroit retirement advisory coordinating Medicare, Social Security, insurance protection, home equity, guaranteed income and estate planning under one roof.